How Does Weak Delegation of Authority Increase Corporate Spending?#
Companies may face financial challenges that are not necessarily caused by declining sales or rising raw material prices, but rather by weaknesses in their internal decision-making and expense approval processes.
When managers and executives operate without clearly defined authority limits, they may enter into contracts, approve purchases, or make financial commitments without obtaining the necessary approvals or assessing whether the decisions align with the company's approved budget.
The problem extends beyond the initial transaction value. It may also include the costs of modifying or cancelling contracts, unexpected financial obligations, and resources allocated to activities that fail to generate the expected economic return.
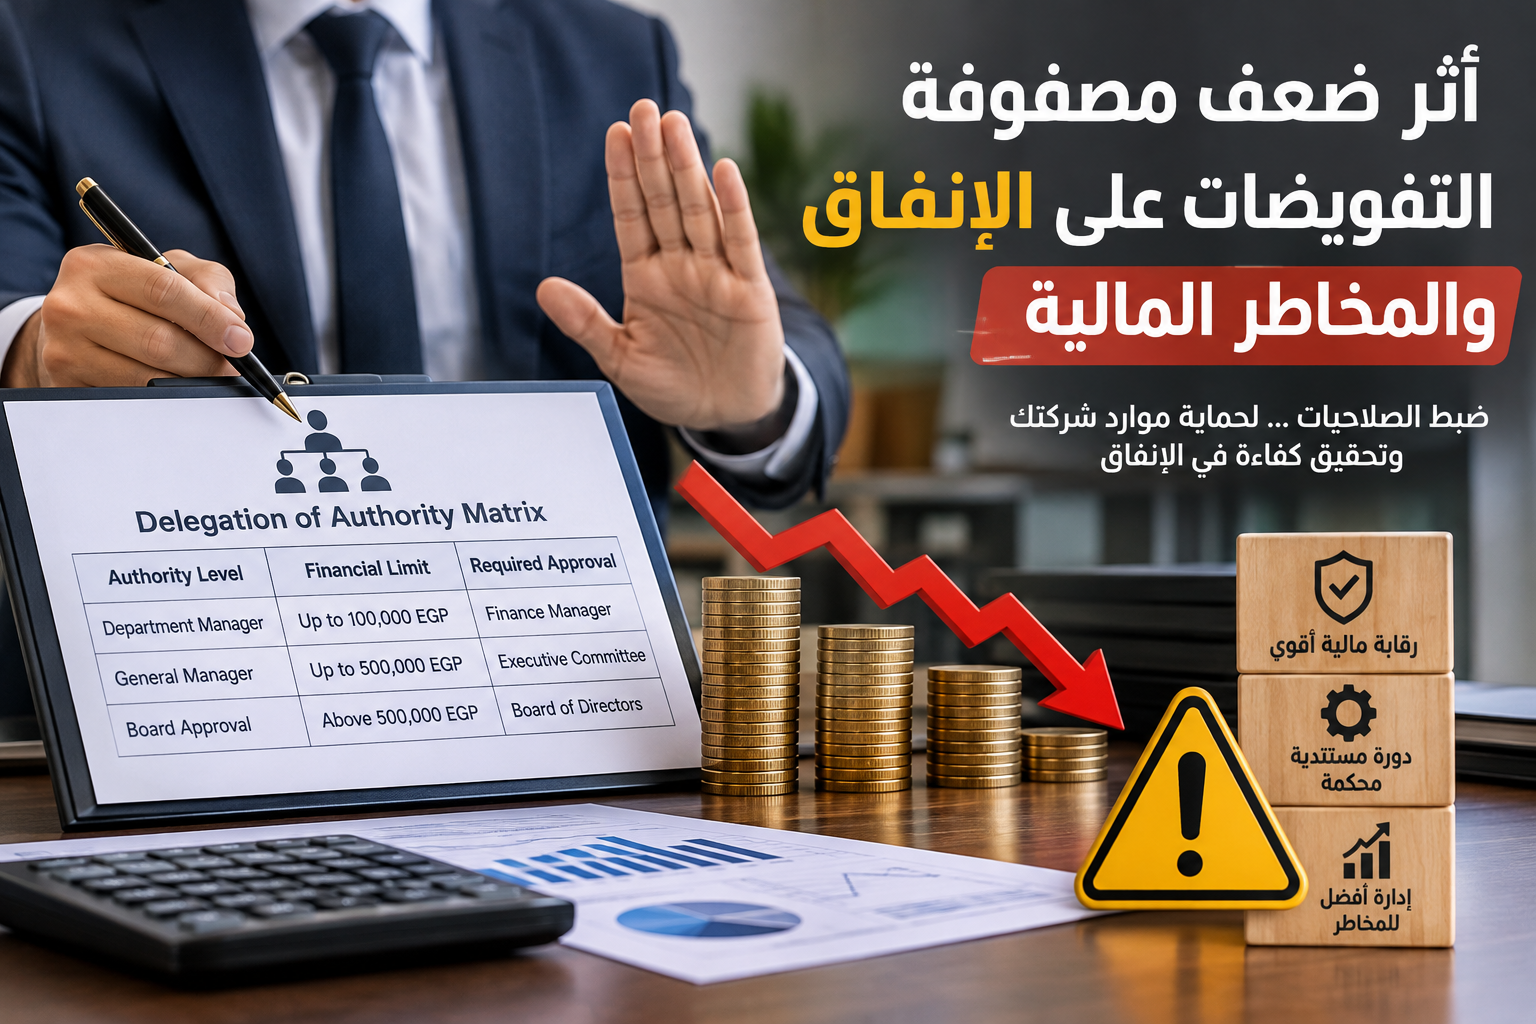
Therefore, a delegation of authority matrix is not merely an administrative document. It is an important financial control mechanism that helps regulate corporate spending and protect company resources.
What Is a Financial and Administrative Delegation of Authority Matrix?#
A delegation of authority matrix is an organizational framework that identifies individuals authorized to make specific decisions or approve transactions within a company, while defining the limits and conditions of their authority.
It may cover several areas, including:
Approval of operational and administrative expenses.
Authorization of purchase orders and contracts.
Approval of long-term financial commitments.
Disposal of company assets and equipment.
Approval of discounts and financial settlements.
Delegation of specific responsibilities to other employees.
Authorization of transactions exceeding approved budget limits.
An effective matrix should not simply identify the responsible employee or their job title. It should also specify the type of transaction, financial limits, required supporting documents, and additional approval levels when certain thresholds are exceeded.
Internal control guidance issued by the US Government Accountability Office (GAO) emphasizes the importance of clearly defined authorization procedures, proper documentation, and ensuring that transactions are approved by individuals acting within their assigned authority.
What Are the Main Financial Risks of Weak Delegation Controls?#
1. Increased Unplanned Expenses
When managers can approve purchases or services without clear financial controls, companies may incur expenses that exceed operational requirements or approved budgets.
This may include unnecessary purchases, duplicated orders, or agreements involving prices and conditions that do not provide the company with the best economic value.
2. Financial Commitments Without Adequate Review
Weak delegation controls may result in contracts, purchase orders, or long-term commitments being approved without properly evaluating their impact on liquidity and cash flow.
Consequently, the company may become responsible for payments that were not included in its financial plan or face additional costs when attempting to amend or terminate agreements.
3. Higher Costs Resulting from Poor Management Decisions
The financial consequences of an inappropriate decision may extend beyond the original transaction.
A company may incur additional expenses related to renegotiating agreements, cancelling contracts, replacing suppliers, or reorganizing operational activities.
4. Increased Risks of Asset and Resource Misuse
When responsibilities for approving asset transactions and resource usage are not clearly defined, companies may experience weaker control over inventory, equipment, and other property.
This can make unauthorized use, financial losses, and resource inefficiencies more difficult to detect.
5. Difficulty Assigning Financial Responsibility
When approvals are not properly documented and authority limits are unclear, it becomes difficult to identify who was responsible for a decision and whether it complied with the company's internal procedures.
This may lead to recurring mistakes and prevent management from addressing the underlying causes of financial irregularities.
How Can Companies Measure the Financial Impact of Weak Delegation of Authority?#
Evaluating the problem requires more than simply counting unauthorized transactions. Companies should measure both the direct and indirect financial costs resulting from weak authorization controls.
The assessment can be divided into several categories:
Assessment Area | Potential Financial Impact |
|---|---|
Unauthorized spending | Expenses outside approved budgets |
Poorly evaluated contracts | Penalties and amendment or cancellation costs |
Unnecessary purchases | Tied-up cash and excess inventory |
Weak asset controls | Asset losses and inefficient utilization |
Repeated administrative errors | Additional operating expenses |
Delayed detection of violations | Increased potential financial losses |
A basic formula for estimating the direct financial impact is:
Direct Financial Impact = Unnecessary Spending + Contract Amendment or Cancellation Costs + Losses Resulting from Inefficient Resource Utilization.
Indirect costs should also be considered, including operational disruption and tied-up liquidity, while avoiding double-counting the same financial loss.
Companies should also distinguish between an expense approved through an improper procedure and an actual economic loss. Not every unauthorized expenditure represents a financial loss of equal value, as a transaction may still provide economic benefits despite weaknesses in its approval process.
Practical Example: How Can Unclear Authority Limits Create Financial Costs?#
Assume that a company manager approves a contract with a supplier worth EGP 800,000 without clear financial authorization or sufficient review of the company's actual requirements.
After implementation begins, management discovers that part of the contracted services is unnecessary and that modifying the agreement will generate additional costs.
The potential financial impact could be distributed as follows:
Cost Item | Amount |
|---|---|
Cost of unnecessary services | EGP 120,000 |
Contract amendment costs | EGP 25,000 |
Additional operating expenses | EGP 15,000 |
Total Financial Impact | EGP 160,000 |
These figures are hypothetical and provided for illustrative purposes only. They do not represent market data or a standard for estimating financial losses.
In this example, the problem is not necessarily the full contract value. Instead, it involves the portion of spending that failed to generate economic value, together with the additional costs resulting from inadequate review and approval procedures.
This illustrates why contractual authority should be linked to approved budgets and actual business requirements rather than being determined solely by an employee's managerial position.
What Indicators Reveal Weak Delegation of Authority Controls?#
Financial management can use several indicators to assess the effectiveness of its delegation framework, including:
The percentage of expenses processed without completing the required approvals.
The value of contracts exceeding approved authorization limits.
The number of transactions amended or cancelled because of approval errors.
The amount of expenses not included in approved budgets.
Repeated approvals of similar transactions without adequate review.
The percentage of transactions lacking supporting documentation.
The value of assets and resources for which responsibility cannot be clearly established.
These indicators should not be evaluated separately. They should be linked to expense analysis, cost reporting, and cash flow assessments to identify the scale and underlying causes of the problem.
How Can Companies Reduce Financial Losses Caused by Weak Delegation Controls?#
Addressing this issue requires an effective control system that connects management authority with financial procedures and accounting documentation.
Companies can take the following steps:
1. Establish a Clear Delegation of Authority Matrix
Identify the individuals responsible for approving different transactions, establish financial limits for each management level, and determine which cases require approval from senior management or the board of directors.
2. Link Financial Approvals to Approved Budgets
Expense reviews should not be limited to confirming that managerial approval exists. They should also verify that sufficient budget allocations are available and that the transaction aligns with the company's operational plan.
3. Improve the Accounting Documentation Cycle
Establish a clear documentation process for every financial transaction, starting with the purchase or contract request, followed by review and approval, delivery or receipt confirmation, expense recording, and payment processing.
4. Separate Financial Responsibilities
Where the company's size and operational structure permit, avoid assigning transaction requests, approvals, asset receipt, and accounting recording to a single individual.
5. Conduct Regular Reviews of Delegated Authority
Review authorization limits whenever management positions or responsibilities change. Revoke outdated delegations and update approval thresholds according to operational and financial developments.
6. Establish a System for Monitoring Authorization Violations
Record transactions processed outside approved authority limits, analyze their causes and financial consequences, and implement corrective procedures to prevent recurrence.
GAO internal control guidance also highlights the importance of proper documentation, appropriate approvals, and the separation of key control responsibilities.
How Do Accounting Documentation Cycles and Cost Accounting Systems Help Control Corporate Spending?#
Effective financial control cannot be achieved simply by establishing authorization limits. Companies also need an accounting documentation cycle that ensures these limits are properly implemented.
A company may have a written delegation of authority matrix, but it may fail to achieve its intended purpose if approvals are undocumented or if the accounting system cannot connect each expense to the department requesting it, the manager approving it, and the relevant budget allocation.
This is where designing accounting documentation cycles and cost accounting systems becomes particularly important.
These systems can help companies:
Define the supporting documents required for each transaction.
Link spending requests to cost centers and approved budgets.
Establish approval levels within financial systems.
Track transactions from initial requests through final payment.
Compare actual expenses with planned expenditure.
Generate reports identifying financial deviations and authorization violations.
Establish clear responsibilities for expense approval and review.
This integration enables management to move beyond recording expenses after they occur toward monitoring financial decisions before implementation and identifying deviations early enough to take corrective action.
When Should a Company Reassess Its Delegation of Authority Matrix?#
Companies should consider reviewing their existing authorization framework when they experience increasing unplanned expenses, repeated contract amendments, or discrepancies between documented authority limits and actual management practices.
The need for reassessment becomes more important when a company expands, opens additional branches, increases its contractual activities, or undergoes organizational restructuring.
In these situations, the solution is not necessarily to reduce managerial authority. Instead, the objective should be to redistribute responsibilities in a way that balances efficient decision-making with appropriate financial oversight.
Conclusion#
Weak delegation of authority can become a continuing source of uncontrolled spending and financial risks, even when a company maintains strong sales performance and a relatively stable financial position.
Addressing this issue begins with measuring the financial impact of poorly controlled decisions, reviewing authorization limits, linking them to budgets and cost centers, and developing an accounting documentation cycle that ensures every transaction is properly recorded, reviewed, and approved.
An effective delegation and financial control framework is not intended to restrict management. Its purpose is to ensure efficient resource utilization, reduce avoidable expenses, and improve the quality of financial and operational decisions.
When companies experience recurring authorization violations or difficulties identifying responsibility for spending, professional assistance can help assess the existing financial system and design accounting documentation cycles and cost accounting systems that match the company's operational structure and business requirements.