How Do Disputes Between Co-Owners Affect Property Value?#
Several investors may jointly own a property in a desirable location with significant market value, yet disagreements between them may prevent the asset from generating its expected financial returns.
One co-owner may exclusively occupy the property, refuse to approve rental arrangements, or obstruct necessary maintenance and improvement decisions.
In other cases, certain owners may wish to sell the property while others insist on retaining it without a clear investment strategy.
These circumstances create financial challenges that extend beyond the property's estimated market price.
They may affect its ability to generate income, the time required to convert the investment into cash, the costs of maintaining the property, and the risks associated with continued ownership.
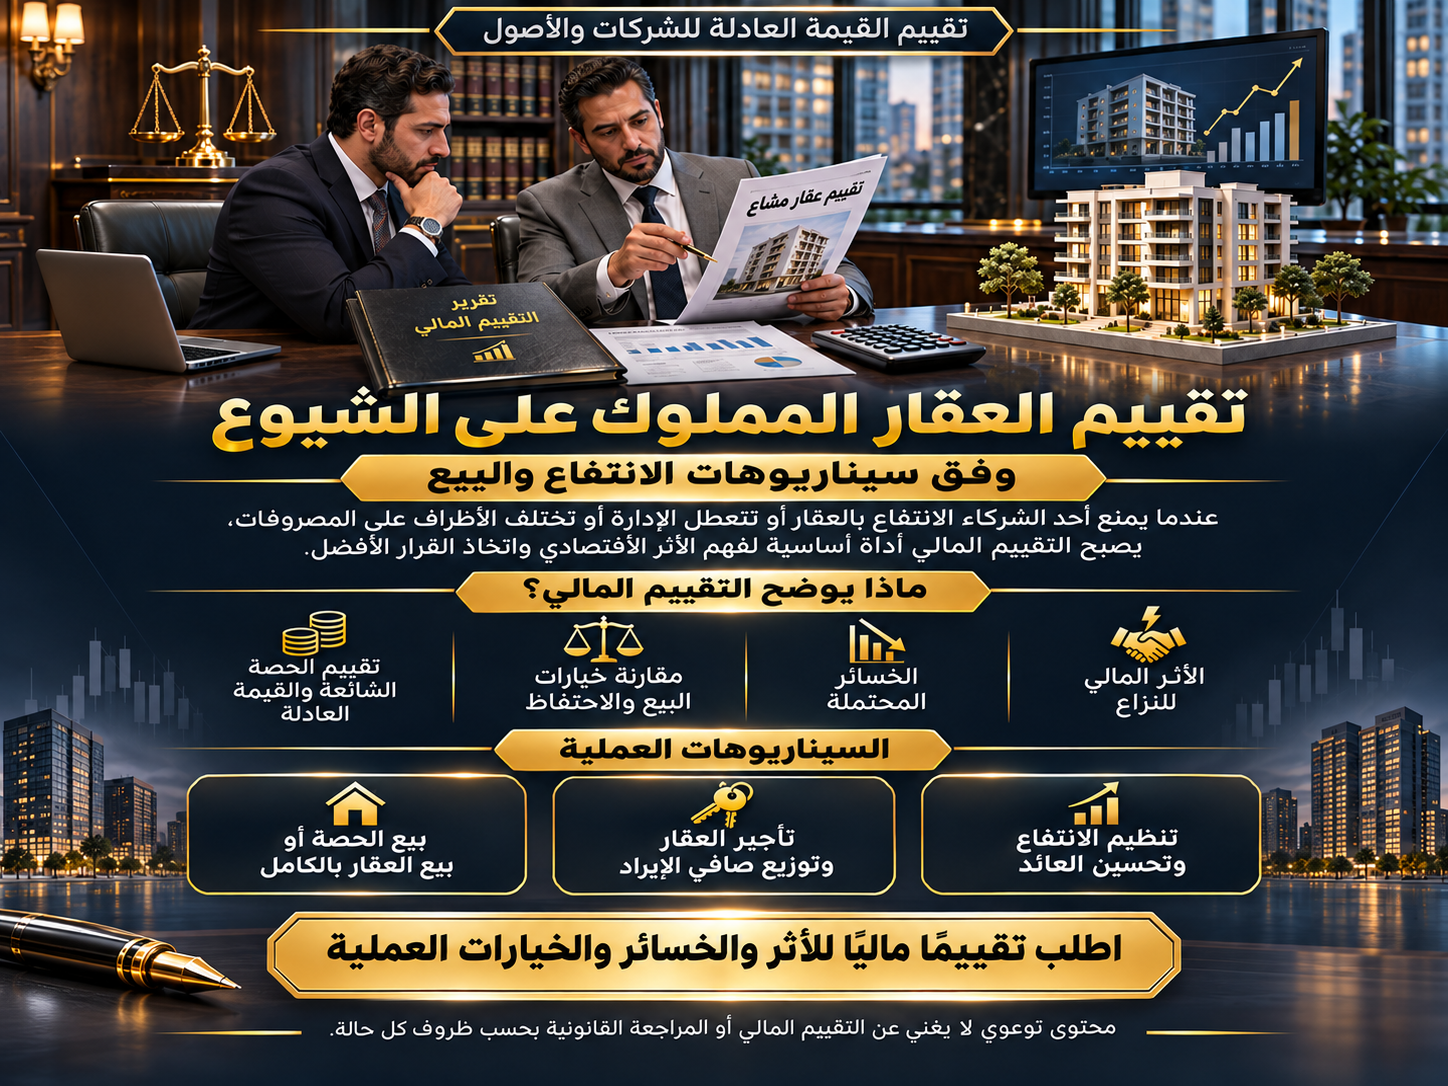
For this reason, the valuation of jointly owned property should not be limited to estimating the market value of the entire asset. It should also identify the specific asset or ownership interest being valued and examine how ownership and usage arrangements affect its economic value and expected returns.
The value of an undivided ownership interest sold independently may differ from its proportional share of the property's overall market value, particularly when management restrictions, limited marketability, or co-ownership disputes affect the investment.
Professional financial valuation helps investors distinguish between the theoretical value of their ownership interests and the economic outcomes they may realistically achieve.
What Is the Difference Between the Value of the Entire Property and an Undivided Ownership Interest?#
When valuing a property owned by multiple individuals, it is essential to distinguish between the value of the property as a complete asset and the value of an individual co-owner's undivided interest.
For example, suppose a property's estimated market value is EGP 10 million, and one investor owns 25% of it.
The investor's proportional share of the property's total value would be EGP 2.5 million.
However, does this necessarily mean the investor can sell that ownership interest for EGP 2.5 million?
Not necessarily.
A prospective buyer of an undivided ownership interest may consider several factors, including the ability to use the property, the level of control over management decisions, cooperation among the remaining co-owners, and the ability to resell the interest in the future.
These factors may cause the price a buyer is willing to pay to differ from the ownership interest's proportional share of the entire property's value.
Guidance published by the UK's Valuation Office Agency recognizes the challenges involved in valuing undivided interests and discusses approaches that begin with the value of the entire property before considering economic disadvantages associated with holding an undivided share.
However, such guidance relates to a UK valuation context and does not establish a mandatory discount or an accepted percentage for the Egyptian real estate market.
It is also important to distinguish between the value of an ownership interest sold independently and its value when all co-owners agree to sell the entire property.
The financial outcomes may differ substantially.
How Is Jointly Owned Property Valued?#
The appropriate valuation methodology depends on the property's characteristics, the purpose of the valuation, the ownership rights being assessed, and the availability of reliable information.
The International Valuation Standards (IVS) recognize three principal valuation approaches: the Market Approach, the Income Approach, and the Cost Approach.
A professional valuer selects the appropriate method or combination of methods according to the nature of the asset and the valuation assignment.
1. Market Approach#
The Market Approach estimates value by analyzing transactions involving comparable properties.
Relevant factors may include location, area, physical condition, intended use, and market characteristics.
Adjustments may be necessary where comparable properties differ from the subject property in economically significant ways.
When evaluating jointly owned property, the valuer must also determine whether the assignment concerns the entire property or an undivided ownership interest.
Comparing the sale price of a complete property with the value of a minority undivided interest without accounting for differences in ownership rights may produce misleading results.
2. Income Approach#
The Income Approach is particularly relevant to investment properties that generate rental income or have reasonably predictable future cash flows.
This approach considers expected rental income, occupancy levels, operating expenses, maintenance costs, and risks affecting the continuity of income.
Depending on the property's characteristics and available data, valuation methods may include capitalization of net operating income or discounted cash flow analysis.
3. Cost Approach#
The Cost Approach may be appropriate for certain properties, particularly where comparable market transactions are limited or the asset has specialized characteristics.
It generally considers the cost of obtaining an asset with equivalent utility, taking into account physical deterioration, functional obsolescence, economic obsolescence, and other relevant factors.
However, the cost of constructing a property is not necessarily equal to its market value.
The valuation must reflect the asset's economic characteristics, ownership rights, market conditions, and relevant limitations.
How Does Restricted Property Use Affect Value and Investment Returns?#
When one co-owner prevents others from using jointly owned property, the consequences may include direct financial losses and indirect economic effects.
Direct financial effects may involve rental income that was not earned, additional expenses incurred by the owners, or increased repair costs resulting from delayed maintenance.
Indirect economic effects may include delayed investment plans, longer marketing periods, reduced attractiveness of an undivided ownership interest to prospective buyers, and greater uncertainty regarding future cash flows.
However, a dispute between co-owners does not automatically reduce the market value of the entire property.
The property may retain substantial market value even when its income-generating potential is temporarily disrupted or an individual ownership interest becomes difficult to sell.
Therefore, a proper assessment should distinguish between:
The value of the entire real estate asset.
The value of the specific ownership interest being assessed.
The economic losses resulting from restricted use or inefficient management.
Failing to distinguish between these elements may result in overstated losses or double counting of the same financial impact.
Practical Example: How Can Lost Income from Restricted Property Use Be Calculated?#
Consider a hypothetical investment property jointly owned by three investors.
The property could generate rental income under normal operating conditions, but disagreements between the co-owners prevent it from being leased for an entire year.
The assumed financial information is as follows:
Hypothetical example — all amounts in Egyptian pounds (EGP)
10,000,000#
Assumed property value
600,000#
Potential annual rental income
120,000#
Annual operating expenses
480,000#
Potential annual net operating income
If the property generates no rental income during the year because leasing arrangements were obstructed, the potential net operating income of EGP 480,000 may serve as an initial indicator of income that was not earned under the hypothetical assumptions.
Potential versus actual net operating income
Illustrative values only; not actual market data
Nevertheless, EGP 480,000 should not automatically be treated as a final financial loss or a legally recoverable amount.
A complete assessment should consider whether the property could realistically have been rented, prevailing market demand, avoided expenses, the reasons for the rental disruption, and any other relevant economic effects.
It is essential to distinguish between potential income that was not generated, lost cash flow, demonstrable economic loss, and compensation that may be awarded through legal proceedings.
What Investment Scenarios Can Maximize the Property's Economic Value?#
Selling jointly owned property is not always the most financially beneficial option.
Similarly, maintaining joint ownership does not necessarily produce the highest investment return.
An informed decision requires comparing potential scenarios based on net financial returns, liquidity, risks, timing, and transaction costs.
Scenario One: Retaining the Property and Regulating Its Use#
Retaining the property may be appropriate when the asset offers favorable growth prospects and the co-owners can establish an effective management arrangement.
Potential advantages include preserving the investment, benefiting from future capital appreciation, and avoiding immediate exit costs.
However, this option requires workable arrangements for property use, management responsibilities, income distribution, and expense allocation.
Scenario Two: Leasing the Property and Distributing Net Income#
Leasing may provide an economically attractive solution when the property's characteristics and applicable legal arrangements permit it.
This scenario requires assessing expected rental income, occupancy rates, operating expenses, maintenance costs, and distributable net cash flows.
The analysis should also consider the risk of future management disputes affecting rental operations.
Scenario Three: Selling an Undivided Ownership Interest Separately#
An investor may wish to obtain liquidity without waiting for all co-owners to agree on selling the entire property.
In this situation, the valuation should focus on the specific ownership interest being offered for sale.
The assessment should examine potential buyers, marketability, applicable legal restrictions, and the economic implications of holding an undivided share.
A valuation adjustment may be appropriate where supported by market evidence and the characteristics of the ownership interest.
However, there is no universal discount percentage applicable to all undivided property interests.
Scenario Four: Selling the Entire Property and Distributing the Proceeds#
Selling the entire property may attract a wider group of potential buyers than selling an undivided interest independently.
This option may be financially preferable where the co-owners can organize a sale and the expected net proceeds exceed the economic benefits of alternative scenarios.
Nevertheless, marketing costs, transaction expenses, applicable obligations, and the expected completion period must be considered.
Financial Comparison of Investment Scenarios#
The following example illustrates how financial outcomes may differ depending on the selected investment strategy.
Assume a property has a total market value of EGP 10 million and an investor owns a 25% interest.
Scenario | Hypothetical Financial Outcome | Main Consideration |
|---|---|---|
Retain and lease the property | EGP 120,000 annual share of potential net operating income | Continued investment |
Sell the undivided interest separately | EGP 2 million, assuming a price 20% below its proportional share | Liquidity with a potential discount |
Sell the entire property | EGP 2.5 million attributable to the investor before transaction costs | Requires an executable property sale |
Continue with restricted use | Potential rental income remains unrealized | Delayed returns and ongoing risks |
All figures are hypothetical. The 20% adjustment is used solely for illustration and does not represent an established market discount or a professionally determined fair value.
The example shows how the proceeds from selling an undivided interest separately may differ from the investor's proportional share of the proceeds from selling the entire property.
However, the figures alone cannot determine which option is financially preferable.
A meaningful comparison must also account for the timing of cash receipts, transaction costs, execution risks, and the time value of money.
Where reliable forecasts are available, financial analysis may use Net Present Value (NPV) or Discounted Cash Flow (DCF) techniques to compare investment alternatives.
How Is the Fair Value of Jointly Owned Property Determined During a Dispute?#
The term fair value is used in different valuation contexts, making it important to establish the relevant valuation basis before beginning the assessment.
Under International Financial Reporting Standard IFRS 13, fair value is defined by reference to the price that would be received to sell an asset in an orderly transaction between market participants at the measurement date.
Fair value is therefore not determined solely by an individual owner's expectations or urgent need for liquidity.
Instead, it reflects assumptions relevant to market participants and the characteristics of the asset or interest being measured.
When applying valuation principles to jointly owned property, the valuer should determine whether the assignment concerns the complete asset, a specific ownership right, or an undivided interest.
The assessment should also examine whether existing disputes, contractual arrangements, or restrictions would affect the assumptions used by market participants.
It is important not to treat fair value, market value, and investment value as interchangeable terms in all circumstances.
Each may involve a different valuation basis and purpose.
Similarly, the economic impact of a dispute should not be deducted twice, such as by reflecting it in projected cash flows and then applying a second unsupported adjustment to the resulting value.
How Can the Financial Impact of Co-Ownership Disputes Be Measured?#
Assessing economic losses generally involves comparing the property's actual financial performance with a reasonable hypothetical scenario in which the disruption did not occur.
The analysis should rely on available evidence and the circumstances prevailing during the period under review.
Several categories may be examined.
Lost Revenue#
This involves estimating the net income the property could reasonably have generated under normal operating conditions and comparing it with actual income.
Additional Expenses#
The assessment identifies costs arising from the dispute or delays in management and maintenance.
Expenses that would have been incurred regardless of the dispute should be distinguished from genuinely additional costs.
Cost of Delay#
Delays in leasing, selling, or redeveloping the property may affect cash flow timing and the present value of expected financial benefits.
Impact of Risk on Value#
Management uncertainty, restricted access, and difficulties in transferring an ownership interest may affect the expectations of prospective buyers and investors.
Opportunity Cost#
Opportunity cost analysis compares the financial outcomes of retaining the property with other investment alternatives that have reasonably comparable risk characteristics and investment horizons.
These categories should not automatically be added together as independent losses.
Some financial effects may overlap, making it necessary to identify their causes and avoid double counting.
What Documents Are Required for an Accurate Joint Property Valuation?#
The reliability of a valuation depends heavily on the availability and quality of information concerning the property, ownership interests, and financial performance.
Relevant documentation may include:
Property ownership documents identifying each co-owner's interest.
Property location, area, and physical condition reports.
Current and historical lease agreements, where available.
Rental income and operating expense records.
Maintenance invoices and repair expenditure.
Agreements governing property management and use.
Information concerning disputes and their effect on occupancy or marketability.
Available purchase offers and verifiable comparable property transactions.
Depending on the assignment, a professional valuation may also require property inspection, market research, and analysis of alternative operating or disposal scenarios.
Published asking prices alone may not provide sufficient evidence of market value without examining their reliability and comparability.
When Is Financial Valuation Necessary Before Selling or Exiting a Joint Property Investment?#
An independent financial valuation may become particularly important when co-owners disagree about a property's value, one investor offers to purchase another's interest, or disputes disrupt income generation.
It may also be valuable where the property forms part of a larger investment portfolio or an investor is evaluating an exit strategy.
A structured valuation helps replace subjective price expectations with a financial assessment supported by data and transparent assumptions.
The purpose is not merely to produce a single value figure.
A well-prepared valuation can also identify uncertainties, explain the assumptions that significantly affect results, and compare the expected financial consequences of different investment strategies.
How Can Fair Value Valuation Services Support Property Owners and Investors?#
Fair Value Valuation of Companies and Assets services can help property owners and investors understand the financial consequences of co-ownership disputes and make informed investment decisions.
Depending on the assignment, the valuation process may include assessing the property or undivided interest, reviewing current and potential income, estimating the impact of restricted use, and comparing retention, leasing, sale, and exit scenarios.
Sensitivity analysis may also be used to examine how changes in sale prices, rental rates, operating costs, marketing periods, and risks affect projected financial outcomes.
The resulting analysis may support negotiations between co-owners, investment exit decisions, or the reassessment of property management strategies.
However, determining legal liability or the amount of legally recoverable compensation remains a separate matter requiring legal assessment based on the circumstances of the dispute.
How Can You Choose the Most Financially Beneficial Option for Jointly Owned Property?#
Joint ownership does not necessarily reduce a property's market value, but it may affect the owners' ability to use the asset, generate returns, or transfer their ownership interests.
When disputes arise over management, expenses, occupation, or selling decisions, comparing alternative financial scenarios becomes essential.
In some cases, regulating property use and maintaining the investment may produce favorable long-term results.
In others, selling the entire asset or exiting an undivided ownership interest may offer greater financial benefits.
The most appropriate decision depends on the value of the ownership interest, expected returns, transaction costs, risks, and the time required to implement each option.