1. How Can Successful Online Sales Turn Into a Cash Flow Crisis?#
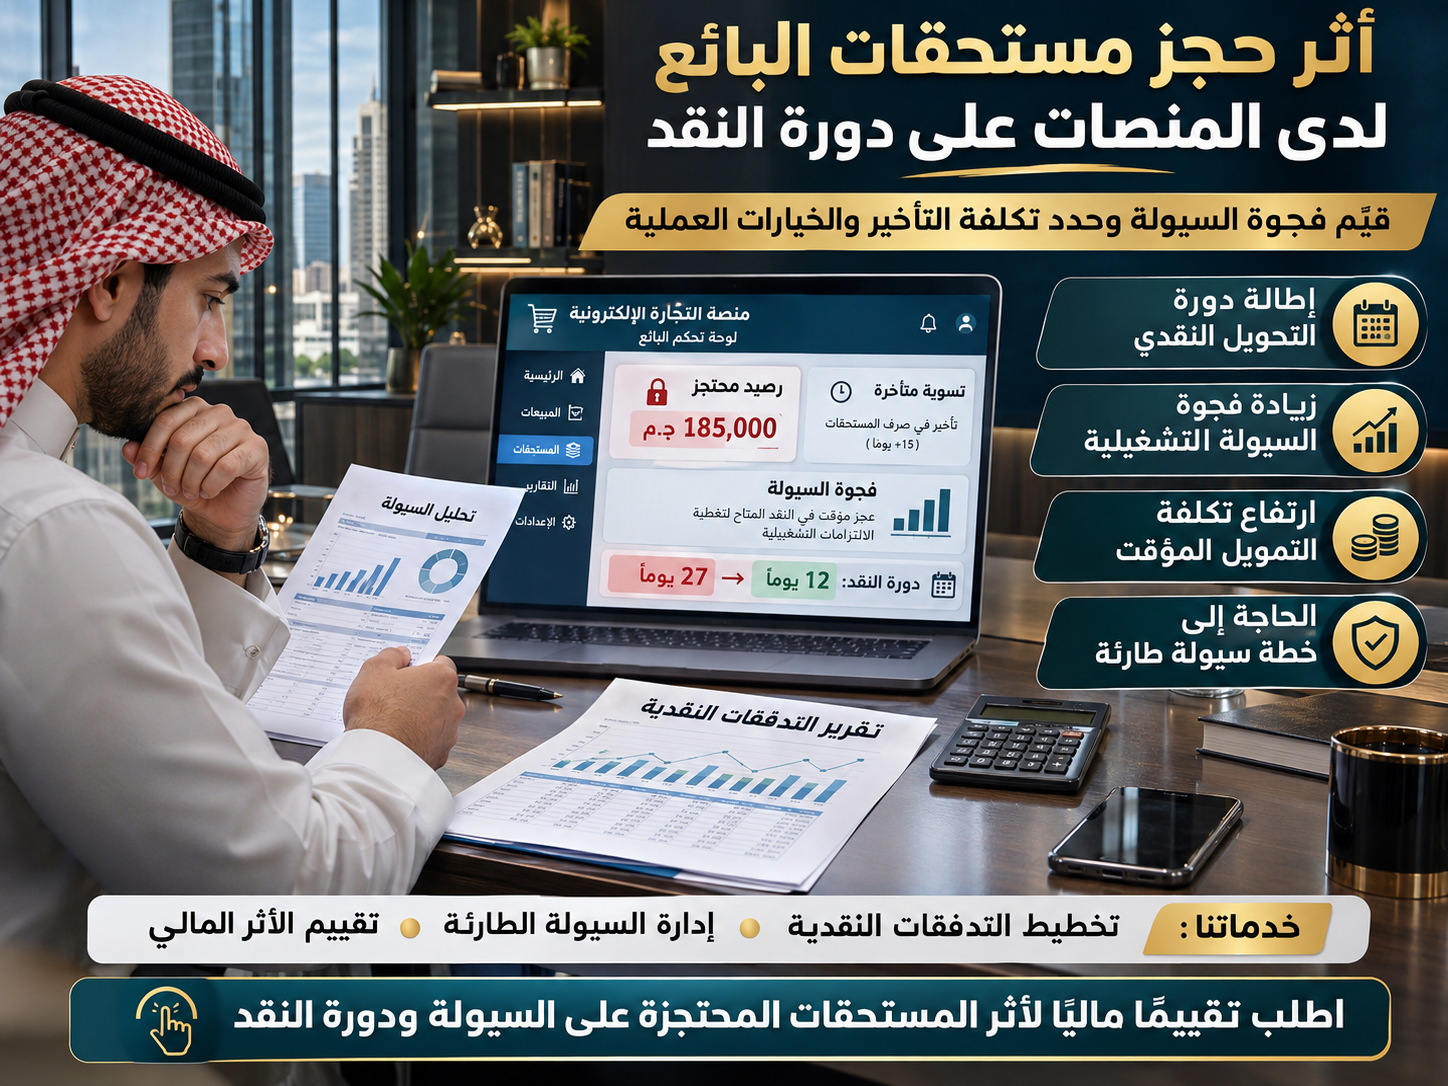
An online store may generate hundreds of thousands of Egyptian pounds in monthly sales while its marketplace dashboard shows continuous growth in orders and revenue.
Despite this positive performance, the business may struggle to pay suppliers, purchase new inventory, or cover operating expenses.
The reason is simple: recorded sales do not necessarily mean cash is available in the company's bank account.
When an e-commerce platform withholds seller payments or delays settlement of completed transactions, a timing gap develops between generating revenue and receiving the corresponding funds.
During this period, the business must continue paying for inventory, shipping, storage, salaries, advertising, and other essential expenses.
The company may consequently need to use its financial reserves, postpone certain payments, or obtain temporary financing.
This creates a critical financial challenge: a business may remain profitable from an accounting perspective while experiencing insufficient cash to support its daily operations.
Therefore, assessing the impact of withheld payments requires more than identifying the total amount frozen by the platform.
Businesses must also evaluate when the money is expected to arrive, how much it costs to replace the missing liquidity, and how settlement delays affect the overall operating cycle.
2. What Is the Cash Conversion Cycle in E-Commerce?#
The Cash Conversion Cycle (CCC) is a financial indicator that measures how long a company takes to recover cash invested in inventory and operations through sales collections, after accounting for the credit period provided by suppliers.
The traditional cash conversion cycle consists of three components.
Days Inventory Outstanding (DIO)
The average number of days a company takes to sell its inventory.
Days Sales Outstanding (DSO)
The average number of days required to collect amounts owed from sales.
Days Payable Outstanding (DPO)
The average number of days a company takes to pay its suppliers.
The standard formula is:
\[ CCC = DIO + DSO - DPO \]
This metric is commonly used to assess working capital efficiency and operating liquidity.
For e-commerce businesses, outstanding marketplace settlements may form part of the receivables collection analysis, depending on the accounting treatment and contractual relationship between the merchant and the platform.
Consequently, delayed marketplace payouts may increase the average collection period and extend the cash conversion cycle, even when customers have already completed their payments.
For digital service businesses that do not hold substantial physical inventory, analyzing collection periods and liquidity gaps may be more relevant than applying the traditional inventory-based CCC without adjustment.
3. How Do Withheld Seller Payments Extend the Cash Conversion Cycle?#
Consider an online retailer with the following financial indicators:
Financial Indicator | Normal Conditions |
|---|---|
Days Inventory Outstanding | 25 days |
Days Sales Outstanding | 7 days |
Days Payable Outstanding | 20 days |
Cash Conversion Cycle | 12 days |
Under normal conditions, the company operates with a cash conversion cycle of 12 days.
Now assume delayed marketplace settlements increase Days Sales Outstanding from 7 to 22 days, while the other indicators remain unchanged.
The revised calculation becomes:
\[ 25 + 22 - 20 = 27\text{ days} \]
Illustrative cash conversion cycle comparison
Before payment delays
12 days
After payment delays
27 days
Illustrative financial figures, not actual market data.
The cash conversion cycle has increased by 15 days.
This means the company requires funding for a longer period before recovering the cash tied up in its operating activities.
However, the increase does not automatically represent an accounting loss.
Instead, it indicates a greater need for working capital or additional liquidity.
This example assumes that the payment delay affects the average collection period for the relevant sales. If only a portion of marketplace transactions is affected, the actual impact should be calculated using weighted averages and the company's financial records.
4. How Can Businesses Calculate the Liquidity Gap Caused by Withheld Payments?#
The total value of withheld funds does not necessarily equal the company's immediate cash shortage.
A business may have substantial outstanding settlements but sufficient cash reserves to continue operating without borrowing.
Another business may face a serious liquidity problem even when a relatively small amount is withheld.
Therefore, the liquidity gap should be calculated using projected cash inflows and payment obligations.
A simplified formula is:
\[ \begin{aligned} \text{Liquidity Gap} ={}& \text{Payments Due During the Period}\\ &-\text{Available Cash and Confirmed Collections} \end{aligned} \]
A positive result indicates a projected funding shortfall.
Practical example
Assume an e-commerce business has the following financial position:
Financial Item | Amount |
|---|---|
Payments withheld by the platform | EGP 200,000 |
Available bank balance | EGP 70,000 |
Other confirmed incoming payments | EGP 30,000 |
Operating payments due | EGP 180,000 |
Projected liquidity gap | EGP 80,000 |
Although the platform is withholding EGP 200,000, the company's projected cash shortage is EGP 80,000 under these assumptions.
This distinction is important for financial decision-making.
The business does not necessarily need to borrow the full withheld amount. Instead, management should determine the actual financing requirement and when that funding will be needed.
Cash flow projections should also consider payment deadlines throughout the period, because a positive month-end cash balance does not eliminate the possibility of temporary weekly cash shortages.
5. What Is the Actual Financial Cost of Delayed Settlements?#
Withheld funds do not necessarily represent a permanent financial loss, particularly if the company ultimately receives the outstanding amounts.
However, delayed access to those funds may generate additional financial and operational costs.
These costs can include:
Alternative Financing Costs
Interest and fees incurred when the company borrows money to cover operating expenses.
Opportunity Costs
Potential returns lost because funds are unavailable for productive business activities.
Additional Operating Expenses
Costs arising from postponed payments, operational adjustments, or other consequences of insufficient liquidity.
Lost Future Sales Opportunities
Potential revenue or contribution margin lost when the business cannot purchase inventory or fulfill customer orders.
Example: Calculating Short-Term Financing Costs
Assume a company requires temporary financing of EGP 150,000 for 30 days at a hypothetical annual interest rate of 24%.
Using simple interest on a 365-day basis:
\[ 150{,}000 \times 24\% \times \frac{30}{365} \]
Estimated financing cost
EGP 2,959
Based on EGP 150,000 borrowed for 30 days at an illustrative annual rate of 24%, excluding additional fees.
The calculation excludes administrative charges, processing fees, and any other financing expenses.
The 24% annual rate is hypothetical and does not represent a current market quotation.
Businesses should also avoid adding opportunity costs and actual financing costs without proper analysis, as this may result in double-counting the same economic impact.
6. Do Withheld Payments Affect E-Commerce Profitability?#
The impact of withheld payments on profitability may be direct or indirect.
From an accounting perspective, delayed collection of a valid receivable does not necessarily reduce previously recognized revenue or profit.
However, if the delay leads to additional borrowing costs or operating expenses, these costs may reduce net profit.
Profitability may also decline if insufficient liquidity prevents the company from purchasing inventory or fulfilling profitable orders.
Illustrative example
Assume an online retailer earns a contribution margin of 20% on additional sales.
If insufficient liquidity prevents the company from fulfilling EGP 100,000 in otherwise achievable sales, the potential lost contribution margin would be:
\[ 100{,}000 \times 20\% = 20{,}000\text{ EGP} \]
However, this amount should not automatically be treated as a confirmed financial loss.
The company would need to establish that the sales were reasonably achievable, that the cash shortage actually prevented fulfillment, and that the contribution margin accurately reflects the relevant variable costs.
Financial assessments should therefore distinguish between confirmed expenses, potential losses, and opportunity costs.
7. How Do Delayed Settlements Affect Working Capital?#
Working capital represents the difference between current assets and current liabilities.
\[ \text{Working Capital} = \text{Current Assets} - \text{Current Liabilities} \]
When a marketplace delays seller payouts, accounting working capital may not immediately decline if the outstanding amounts remain recognized as current receivables.
However, the composition of current assets changes.
A larger portion of the company's assets remains tied up in unsettled payments rather than available cash.
As a result, actual liquidity may deteriorate even when the reported total working capital remains relatively stable.
The business may then require additional financing to meet short-term obligations.
This distinction between receivables and immediately available cash is particularly important for businesses with substantial operating expenses.
The risk becomes greater when settlement delays coincide with increasing inventory requirements, supplier obligations, or periods of strong seasonal demand.
8. When Do Delayed Settlements Become a Threat to Business Continuity?#
There is no single settlement delay period that is equally dangerous for every business.
The consequences depend on daily operating expenses, available cash reserves, reliance on a particular marketplace, and access to alternative financing.
Important warning indicators include:
Declining cash reserves relative to upcoming obligations.
Increasing overdue marketplace receivables.
Repeated reliance on borrowing to cover operating expenses.
Delays in supplier payments or inventory purchases.
A growing proportion of expected collections being withheld.
Recurring settlement delays without reliable payout dates.
A useful measure is the number of days current cash reserves can cover operating payments.
\[ \text{Cash Coverage Days} = \frac{\text{Available Cash}}{\text{Average Daily Cash Payments}} \]
For example, if a business has EGP 90,000 available and its average daily operating payments are EGP 6,000, the available cash would cover approximately 15 days of payments, assuming no additional cash inflows.
This does not necessarily mean the business will stop operating after 15 days.
However, it highlights the importance of preparing a cash flow forecast that considers future collections and payment obligations.
9. What Financial Options Are Available When Seller Payments Are Withheld?#
There is no universal solution to marketplace settlement delays.
The appropriate response depends on the size and duration of the liquidity gap, the cost of available financing, and the likelihood of receiving the withheld funds.
Financial Option | Potential Advantage | Potential Cost or Risk |
|---|---|---|
Using cash reserves | Provides liquidity without borrowing | Reduces financial safety reserves |
Negotiating supplier terms | Delays certain cash outflows | May affect discounts or business relationships |
Short-term financing | Covers temporary cash shortages | Creates interest costs and repayment obligations |
Reducing nonessential expenses | Preserves available cash | May postpone growth initiatives |
Diversifying payment and sales channels | Reduces dependence on one platform | May require additional operating and integration costs |
Negotiating settlement with the platform | Addresses the original source of the cash shortage | Resolution may remain uncertain or delayed |
Businesses may also explore working capital facilities or receivables-based financing where commercially suitable and available.
However, eligibility, contractual restrictions, financing costs, and repayment risks must be assessed carefully.
The goal should be to compare the total economic cost of each option rather than selecting financing solely because it provides faster access to cash.
10. Is Temporary Financing Better Than Waiting for Marketplace Payments?#
The decision depends on whether the benefits of obtaining immediate liquidity outweigh the financing costs and risks.
Assume a business needs EGP 100,000 to replenish inventory.
Management has two potential options.
Option One: Wait for the Marketplace Settlement
The company avoids direct financing costs but may postpone purchasing inventory.
This could result in lost contribution margin if the business cannot fulfill otherwise profitable customer orders.
Option Two: Obtain Short-Term Financing
The business can purchase inventory immediately but must pay interest and possibly additional financing fees.
The decision should compare the expected additional contribution margin with the total financing cost, while considering demand uncertainty and repayment risk.
If financing costs exceed the expected economic benefit, borrowing may not be commercially justified.
Conversely, temporary financing may be appropriate if it prevents substantial operational disruption or supports confirmed orders with attractive margins.
However, the company must also consider whether it can repay the financing if marketplace settlements are delayed longer than expected.
11. Financial Scenario Analysis: How Settlement Delays Increase Costs#
Scenario analysis helps businesses estimate the impact of different settlement delays.
Assume a company must finance a fixed cash shortage of EGP 200,000 at a hypothetical annual interest rate of 24%.
The following calculations use simple interest over a 365-day year and exclude additional fees.
Settlement Delay | Estimated Financing Cost |
|---|---|
7 days | EGP 921 |
15 days | EGP 1,973 |
30 days | EGP 3,945 |
This example demonstrates that financing costs generally increase as the funding requirement continues.
However, the actual cost may differ if the company draws financing gradually, receives partial marketplace settlements, or experiences changes in its cash requirements.
Daily or weekly cash flow forecasts can therefore provide more accurate results than assuming that the full financing amount remains outstanding throughout the entire delay.
12. How Can Businesses Develop an Emergency Liquidity Plan?#
When settlement delays begin to affect operations, companies should prepare a short-term liquidity management plan.
The process begins with identifying available cash, confirmed incoming payments, and obligations falling due over the coming weeks.
Payments should then be classified according to their operational importance and the consequences of postponement.
Supplier payments, payroll, and essential services may require greater priority than certain discretionary expenses.
Businesses should also prepare several settlement scenarios.
These may include receiving funds on the expected date, experiencing an additional delay, or continuing to have a portion of the balance withheld.
For each scenario, management should identify the expected cash shortage, its timing, and the potential sources of funding.
Regular comparisons between projected and actual cash flows are essential for updating the plan as new information becomes available.
13. How Can Businesses Reduce Dependence on a Single E-Commerce Platform?#
Relying heavily on one marketplace for sales and payment collection can create financial concentration risk.
Even when the platform generates substantial revenue, interruptions in settlement may affect the liquidity of the entire business.
Companies can consider diversifying sales and collection channels according to their business models.
Potential approaches include developing an independent online store, using additional payment providers, expanding direct sales channels, or distributing sales across multiple marketplaces.
However, diversification also involves costs.
New channels may require advertising expenditure, technical integration, additional inventory management, and customer support resources.
Therefore, businesses should compare these costs with the potential benefits of reducing payment concentration risk and improving cash flow stability.
The objective is not necessarily to abandon successful marketplaces but to prevent settlement disruptions at a single platform from creating a company-wide liquidity crisis.
14. How Can Financial Analysis Measure Losses Caused by Withheld Payments?#
Professional financial analysis helps businesses convert delayed settlement problems into measurable financial indicators.
Rather than focusing exclusively on the outstanding balance, an assessment can examine the effect on the cash conversion cycle, working capital requirements, financing expenses, and the ability to fulfill customer orders.
A comprehensive assessment may include cash flow forecasting, receivables aging analysis, settlement delay cost calculations, and operational risk evaluation.
It can also compare financing alternatives, supplier negotiations, expense reductions, and inventory management adjustments.
Importantly, a financial report should distinguish between recoverable receivables, actual incurred costs, potential losses, and unrealized business opportunities.
This distinction helps management make informed financial decisions and may provide useful supporting analysis when the business needs to negotiate a commercial settlement or pursue a contractual claim against the platform.
Conclusion: The Problem Is Not Only How Much Money Is Withheld, but When It Becomes Available#
Withheld seller payments can extend the cash conversion cycle and increase working capital requirements even when an e-commerce business remains profitable.
The financial consequences may go beyond the unavailable balance and include additional financing expenses, operating costs, and lost commercial opportunities.
Businesses should therefore calculate their liquidity gaps, identify upcoming payment obligations, and evaluate financing alternatives before making borrowing or cost-reduction decisions.
A well-designed cash flow management strategy can help preserve business continuity while outstanding marketplace settlements remain unresolved.
If e-commerce platforms or payment service providers are delaying your company's settlements, consider requesting a professional financial assessment to measure the impact on your cash conversion cycle, identify actual and potential losses, evaluate financing alternatives, and develop an emergency liquidity plan to protect your business operations.