1. Can Your Most Successful Marketplace Become a Financial Risk?#
An e-commerce business may begin selling products through a well-established online marketplace and experience consistent growth in orders and revenue.
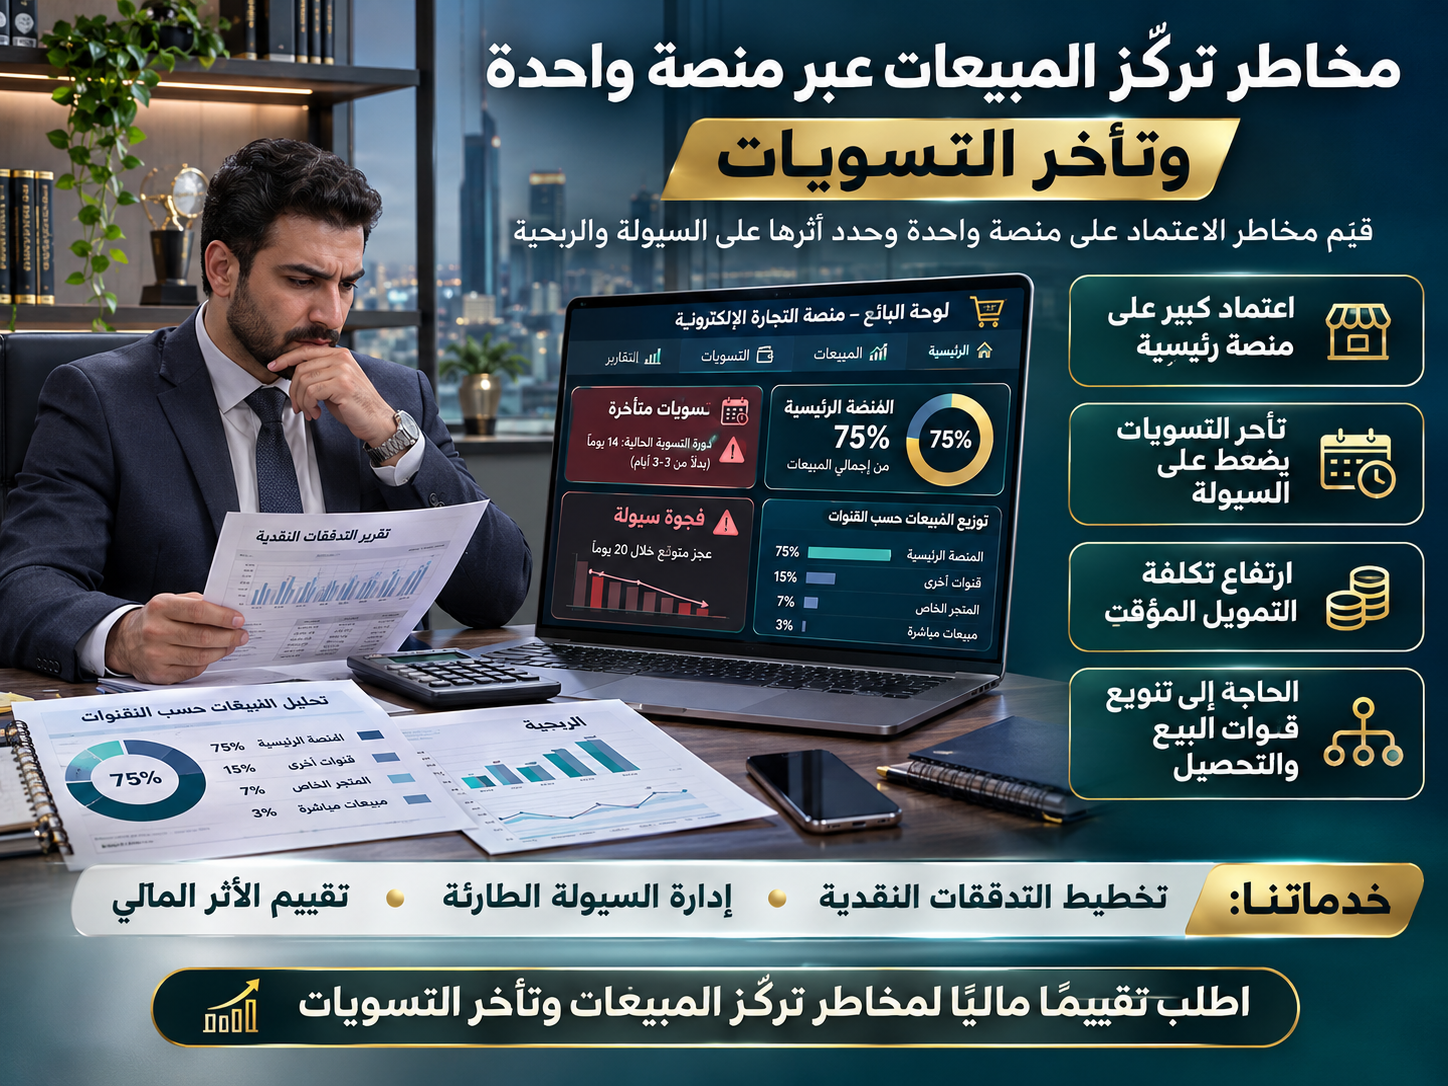
Over time, the marketplace may become the company's primary source of customers and sales, potentially accounting for 70% or 80% of total revenue.
From a commercial perspective, this arrangement can appear highly beneficial.
The marketplace may provide access to a large customer base, order management tools, payment processing services, and sometimes logistics and fulfillment solutions.
However, financial problems can emerge when the platform delays seller payouts, freezes part of the available balance, or introduces disputed deductions.
In such circumstances, the issue may affect more than a limited number of transactions.
It can disrupt most of the company's expected cash inflows.
Operating expenses, supplier obligations, payroll, and inventory purchases continue to require payment even while the platform holds funds.
This is the central risk of sales concentration: strong performance through one marketplace does not necessarily mean a business has sufficient financial flexibility to withstand disruptions affecting that platform.
Therefore, businesses should evaluate marketplaces not only by their sales volumes but also by settlement reliability, collection costs, profitability, and the proportion of operating liquidity dependent on each channel.
2. What Is Sales Concentration Risk in E-Commerce?#
Sales concentration refers to the extent to which a company's revenue depends on a particular sales channel, marketplace, or customer source.
It is important to distinguish sales channel concentration from customer concentration.
A marketplace may connect a business with thousands of individual customers. Nevertheless, dependence on the platform itself can create a shared risk affecting access to customers, sales operations, or payment collection.
In e-commerce, concentration risk can generally be divided into three categories.
Sales Concentration
A substantial proportion of the company's revenue comes from one marketplace.
Payment Collection Concentration
The company depends on a particular platform or payment provider to receive most of its sales proceeds.
Operational Concentration
Order management, inventory, fulfillment, shipping, or customer access depends heavily on one platform.
These risks may exist independently or simultaneously.
For example, a business may sell through three marketplaces but use the same payment service provider for most collections.
In that situation, its sales channels are diversified, but payment collection concentration remains high.
For this reason, revenue sources and cash collection channels should be analyzed separately.
3. How Can Businesses Calculate Marketplace Sales Concentration?#
Sales concentration can be measured by calculating the proportion of total business revenue generated through a particular marketplace.
The basic formula is:
\[ \text{Sales Concentration Ratio} = \frac{\text{Marketplace Sales}}{\text{Total Sales}} \times 100 \]
Illustrative example
Assume an e-commerce business generates EGP 1,000,000 in monthly sales, distributed as follows:
Sales Channel | Monthly Sales | Share |
|---|---|---|
Primary marketplace | EGP 750,000 | 75% |
Independent online store | EGP 150,000 | 15% |
Other marketplaces | EGP 100,000 | 10% |
Total | EGP 1,000,000 | 100% |
Illustrative monthly sales distribution
■ Independent store
■ Other marketplaces
■ Primary marketplace
Hypothetical data for illustration.
In this example, the company generates 75% of its sales through its primary marketplace.
This level of dependency warrants closer financial examination, but it does not automatically indicate the same degree of risk for every business.
Risk also depends on settlement reliability, profit margins, cash reserves, and the company's ability to shift sales to alternative channels.
Businesses should calculate their concentration ratios monthly and quarterly to identify changes over time.
4. Why Are Delayed Settlements More Dangerous When Sales Are Concentrated?#
When a business collects revenue through several independent channels, cash received from one source may partially compensate for delays affecting another.
However, when most revenue flows through a single platform, delayed settlements can disrupt a substantial portion of expected collections.
The problem becomes more serious when the company must pay for inventory, shipping, advertising, and salaries before receiving its sales proceeds.
Potential financial consequences include:
Reduced cash available to meet short-term obligations.
Increased working capital financing requirements.
Delayed inventory purchases or order fulfillment.
Higher short-term borrowing costs.
Potential loss of future sales opportunities.
Greater sensitivity to additional settlement disruptions.
These outcomes are not inevitable.
Their severity depends on the company's financial position, access to alternative funding, and cash management capabilities.
Importantly, funds appearing in marketplace statements may remain unavailable for immediate business use.
As a result, the timing of cash collections can become as important as the amount of revenue generated.
5. How Can Businesses Calculate the Liquidity Gap Caused by Marketplace Settlement Delays?#
Financial analysis should begin by identifying expected cash inflows and comparing them with obligations falling due during the same period.
A simplified formula is:
\[ \begin{aligned} \text{Liquidity Gap} ={}& \text{Payments Due}\\ &-\text{Available Cash and Confirmed Collections} \end{aligned} \]
A positive result indicates a projected funding shortfall.
Practical example
Assume a company relies on one marketplace for most sales and is experiencing delayed payouts totaling EGP 300,000.
Its projected cash position for the following two weeks is:
Financial Item | Amount |
|---|---|
Payments withheld by the marketplace | EGP 300,000 |
Available cash | EGP 90,000 |
Confirmed collections from other channels | EGP 40,000 |
Payments due | EGP 230,000 |
Projected liquidity gap | EGP 100,000 |
Although the platform is withholding EGP 300,000, the company's projected liquidity gap is EGP 100,000 under these assumptions.
This distinction helps management determine how much financing is actually required rather than attempting to replace the entire withheld balance.
However, cash flow forecasts must reflect individual payment dates, because temporary shortages may be greater on certain days.
6. What Is the Financial Cost of Relying on One Marketplace During Settlement Disruptions?#
The total value of withheld funds should not automatically be classified as a financial loss.
The company may still be entitled to receive those funds at a later date.
Instead, the actual economic cost generally arises from the consequences of delayed cash availability.
These costs may include:
Alternative Financing Costs
Interest and fees incurred when borrowing funds to cover operating expenses.
Opportunity Costs
Potential returns lost because the company cannot use its cash for productive business activities.
Additional Operating Expenses
Costs associated with payment rescheduling, changes in purchasing plans, or operational adjustments.
Lost Contribution Margin
Potential earnings lost when the business cannot fulfill otherwise achievable sales because of insufficient liquidity.
Corrective Action Costs
Expenses incurred when urgently establishing alternative sales or payment channels.
Financial assessments should separate confirmed costs from estimated losses and avoid double-counting the same economic impact.
7. Example: Calculating Financing Costs Caused by Delayed Settlements#
Assume a business requires EGP 200,000 in temporary financing to cover part of the funds withheld by its primary marketplace.
The hypothetical annual financing rate is 24%, and the delay lasts 30 days.
Using simple interest:
\[ \text{Financing Cost} = 200{,}000 \times 24\% \times \frac{30}{365} \]
Estimated financing cost
EGP 3,945
Based on EGP 200,000 for 30 days at a hypothetical annual rate of 24%, excluding additional fees.
The cost may increase if the delay continues or the company incurs additional financing charges.
Conversely, it may decrease if partial marketplace settlements reduce the amount borrowed.
The interest rate used in this example is hypothetical and does not represent an actual market quotation.
Where financing balances change throughout the month, calculating interest using daily outstanding amounts may provide a more accurate assessment.
8. How Does Marketplace Concentration Affect Business Profitability?#
Relying on one marketplace may offer meaningful operational advantages.
Large platforms can provide access to customers at relatively efficient marketing costs and may offer logistics services that reduce certain operating expenses.
However, these benefits should be evaluated alongside the associated financial risks.
Revenue alone is not sufficient to assess a channel's economic performance.
Marketplace commissions, fulfillment costs, refunds, advertising expenses, and settlement reliability may differ significantly between channels.
Businesses should therefore calculate profitability or contribution margin separately for each sales channel.
Illustrative example
Suppose a marketplace generates EGP 750,000 in monthly sales with a contribution margin of 18%.
The monthly contribution margin would be:
\[ 750{,}000 \times 18\% = 135{,}000\text{ EGP} \]
If settlement delays require additional financing, these costs may reduce the economic return associated with that channel.
This does not necessarily make the marketplace unprofitable.
Instead, financing costs and liquidity risks should be incorporated into the channel's overall financial assessment.
A smaller sales channel may offer faster and more predictable cash collections, making it valuable for improving liquidity diversification.
9. Is Diversifying Sales Channels Financially Better Than Relying on One Marketplace?#
Diversification may reduce concentration risk, but it requires financial evaluation before implementation.
Developing an independent online store or joining additional marketplaces may involve technical, marketing, and operational expenses.
The existing marketplace may also provide more efficient customer acquisition than newly established channels.
Therefore, businesses should compare their options using relevant financial and operational criteria.
Evaluation Criteria | Single Marketplace | Diversified Sales Channels |
|---|---|---|
Operating costs | May be lower | May increase due to additional channels |
Customer access | Depends on the platform's audience | Distributed across multiple sources |
Settlement risk | More concentrated | May decrease if payment channels are independent |
Inventory management | May be simpler | May require additional coordination |
Operational flexibility | Depends heavily on one platform | May improve through diversification |
Marketing expenses | Depend on marketplace arrangements | May require additional investment |
Diversification does not necessarily reduce payment collection risk if all channels continue using the same payment provider or operational infrastructure.
For that reason, companies should consider diversifying both sales channels and collection arrangements.
The objective is to reduce financial vulnerability without creating unnecessary operating costs.
10. How Can Businesses Compare Diversification Costs With Potential Financial Losses?#
A financial model can help determine whether developing additional sales channels is economically justified.
The model should include setup costs, recurring operating expenses, expected sales, contribution margins, and potential improvements in liquidity resilience.
Hypothetical example
Assume launching an independent sales channel requires:
Cost Component | Amount |
|---|---|
Initial setup investment | EGP 60,000 |
Additional monthly operating and marketing expenses | EGP 8,000 |
Annual recurring expenses | EGP 96,000 |
Total first-year cash cost | EGP 156,000 |
The first-year cost is calculated as:
\[ 60{,}000 + (8{,}000 \times 12) =156{,}000\text{ EGP} \]
However, this amount must be compared with the expected financial contribution generated by the new channel.
If the channel attracts genuinely additional customers, its contribution margin should be calculated after variable costs.
If sales merely shift from the existing marketplace to the independent store, the financial model should measure the difference in profitability between the two channels rather than treating all transferred sales as incremental revenue.
The potential value of reduced settlement risk should also be considered without assuming that every possible financial loss would otherwise occur.
11. How Can Scenario Analysis Measure Marketplace Concentration Risk?#
Scenario analysis helps businesses test their ability to withstand settlement delays affecting their primary marketplace.
Assume a company expects EGP 300,000 in marketplace settlements but needs temporary financing of EGP 150,000 throughout the delay.
Using a hypothetical annual financing rate of 24%, the estimated costs would be:
Scenario | Settlement Delay | Estimated Financing Cost |
|---|---|---|
Limited delay | 7 days | EGP 690 |
Moderate delay | 15 days | EGP 1,479 |
Extended delay | 30 days | EGP 2,959 |
The example illustrates how financing costs increase as settlement delays continue, even when the withheld balance remains unchanged.
Actual costs depend on the daily funding requirement and the period during which financing is used.
Scenario analysis should also consider partial payment suspensions, staggered settlements, and seasonal increases in operating expenses.
12. Which Financial Indicators Reveal Excessive Marketplace Dependency?#
Companies can establish a financial monitoring dashboard to identify increasing concentration and liquidity risks.
Sales Concentration Ratio
Measures the percentage of total revenue generated through the primary marketplace.
Collection Concentration Ratio
Measures the proportion of expected cash collections dependent on the primary payment channel.
Average Settlement Period
Tracks the average time between payment entitlement and actual receipt of funds.
Overdue Settlement Ratio
Compares settlements that have passed their contractual due dates with total amounts due.
Cash Coverage Days
Estimates how long available cash can cover operating payments under specified assumptions.
Financing Costs Related to Delays
Measures additional financing expenses directly attributable to settlement disruptions.
Tracking these indicators over time can help management detect emerging risks before they develop into significant cash shortages.
There is no universal sales concentration percentage that can be considered safe for every business.
Appropriate internal warning levels should reflect the company's operating model, margins, liquidity reserves, and financial flexibility.
13. How Can Businesses Develop an Emergency Liquidity Plan?#
Companies that depend heavily on a single marketplace should establish a structured financial response plan for settlement delays.
The process can begin with an 8-to-13-week cash flow forecast, depending on the nature of the business.
The forecast should include available cash, expected collections from each sales channel, operating expenses, supplier payments, and financing obligations.
The emergency liquidity plan can follow five practical stages.
1. Identify Available Cash
Determine the amount of money immediately accessible to the business without including receivables whose settlement dates remain uncertain.
2. Prioritize Financial Obligations
Distinguish between payments essential to business continuity and expenses that can be postponed without causing major operational disruption.
3. Evaluate Settlement Delay Scenarios
Calculate expected cash shortages if settlements are delayed by one week, two weeks, or a month.
4. Identify Funding Alternatives
Evaluate existing reserves, supplier payment negotiations, and suitable short-term financing options.
5. Review and Update Forecasts
Compare actual cash movements with projections and adjust financial decisions when settlement conditions change.
The plan should not depend entirely on an uncertain assumption that the marketplace will release all outstanding funds on a particular date.
Instead, management should evaluate whether the company can continue operating if the delay lasts longer than expected.
14. Can Businesses Reduce Concentration Risk Without Leaving Their Primary Marketplace?#
Reducing marketplace dependency does not necessarily require abandoning the platform that generates the highest sales.
The primary marketplace may remain strategically valuable, and leaving it could create greater financial disadvantages than continuing to operate with improved risk management.
Businesses may consider gradually increasing cash reserves, improving settlement forecasts, reviewing platform fees, and distributing marketing expenditure more effectively.
They may also develop an independent online store alongside their existing marketplace operations.
Companies with substantial transaction volumes may have opportunities to negotiate clearer settlement arrangements or improved commercial terms.
Diversifying payment collection methods may also help, provided the additional costs do not exceed the expected benefits.
The objective is not to achieve the lowest possible marketplace concentration at any cost, but to balance channel profitability, liquidity risk, and business continuity.
15. How Can Professional Financial Assessment Support Diversification Decisions?#
Choosing between continued reliance on one marketplace and investment in additional sales channels requires more than comparing monthly revenues.
A primary marketplace may offer attractive profit margins while exposing the company to settlement delays.
An alternative channel may provide faster cash collections but require higher marketing or operating expenditure.
Professional financial analysis can compare channel profitability, customer acquisition costs, settlement reliability, working capital requirements, and the additional costs associated with payment delays.
It can also assess revenue concentration, calculate potential liquidity gaps, and prepare cash flow forecasts under normal and adverse operating scenarios.
An effective financial report should distinguish between three categories:
Financial losses already incurred.
Expected costs under defined settlement scenarios.
Potential benefits of diversifying revenue and collection channels.
This analysis can help management make informed decisions about new channel investments, financing policies, and additional cash reserves.
It may also support discussions with business partners, investors, and financing institutions regarding settlement risks and liquidity requirements.
Conclusion: Sales Diversification Protects Liquidity When Supported by Financial Analysis#
Relying on a single e-commerce marketplace can provide substantial opportunities for business growth.
However, it may also increase financial vulnerability when most sales and collections depend on that platform.
If settlements are delayed or funds are withheld, the company may experience liquidity shortages and increased financing costs even while maintaining healthy sales and accounting profits.
Diversification is not automatically the best solution in every situation.
Businesses should compare the costs of establishing additional channels with their expected profitability and ability to reduce financial risk.
Effective decision-making requires measuring sales and collection concentration, analyzing cash flow gaps, evaluating settlement delay scenarios, and testing the company's ability to meet its obligations.
If your business depends on one marketplace for most of its revenue or regularly experiences delayed settlements, consider requesting a professional financial assessment to measure sales concentration risk, estimate potential losses and financing costs, compare channel diversification options, and develop a practical cash flow and emergency liquidity management strategy.