1. What Happens When a Payment Service Provider Refuses to Settle Completed Transactions?#
E-commerce merchants and digital businesses depend on payment service providers to collect customer payments and facilitate the transfer of sales proceeds.
Under normal circumstances, a customer completes a payment, the transaction is recorded in the payment system, and the relevant amount enters the financial settlement process according to the agreement with the payment provider.
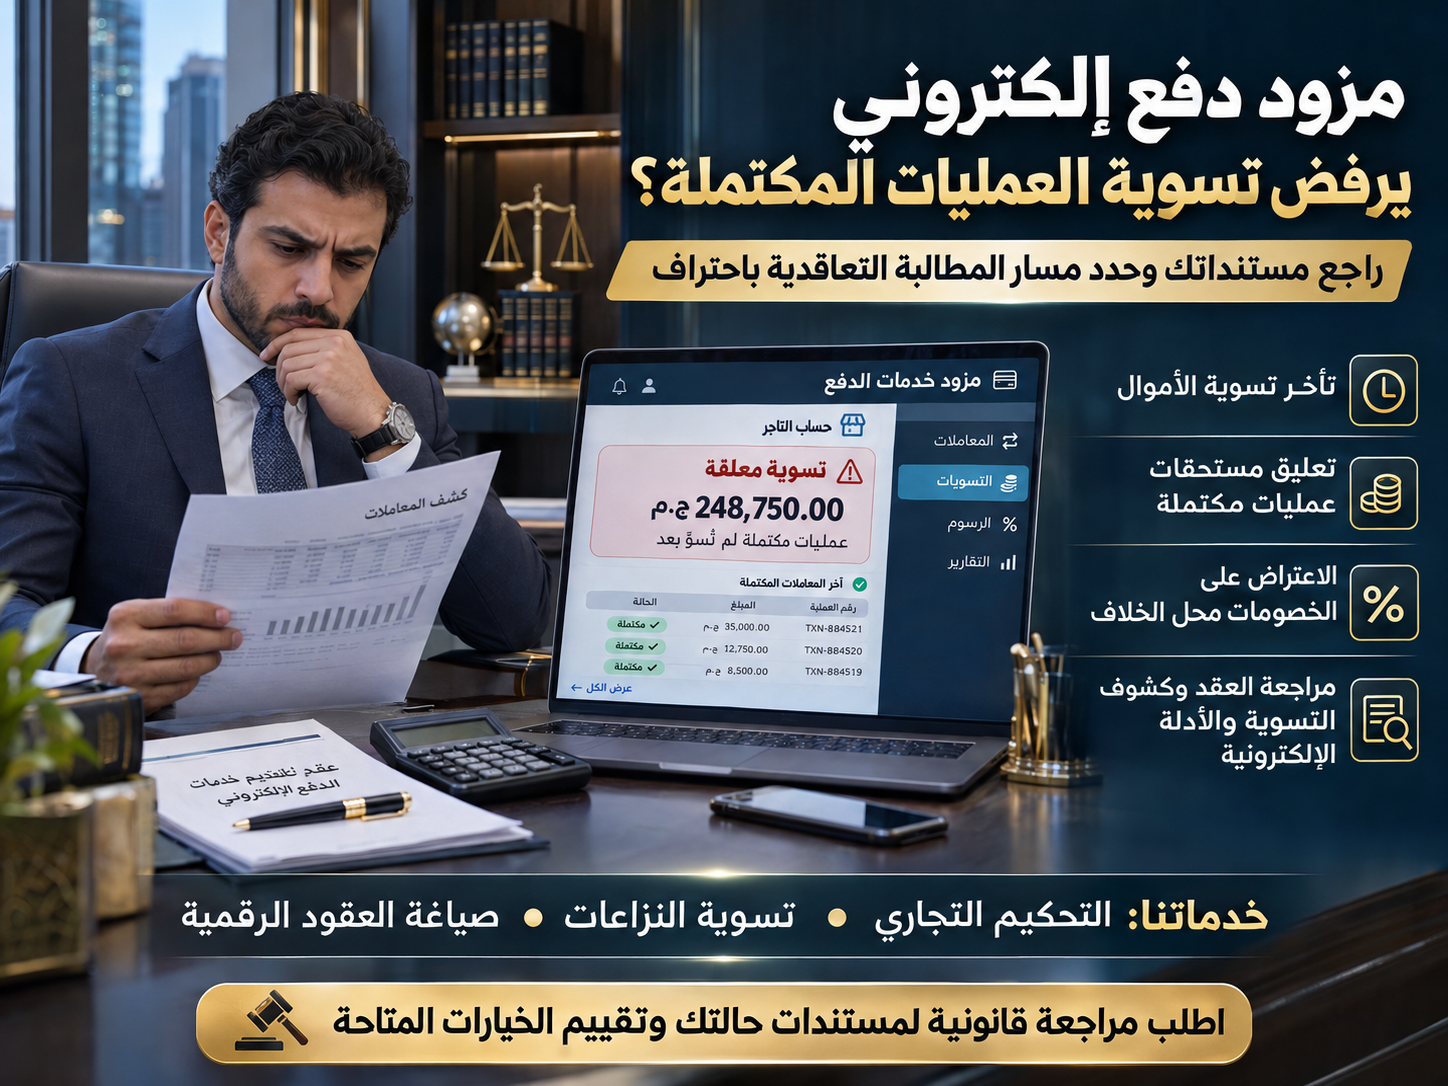
However, businesses may encounter situations where transactions appear successful but the corresponding funds are not transferred to their bank accounts within the expected timeframe.
In some cases, the provider may suspend settlement, impose additional deductions, or transfer amounts that do not match the merchant's transaction reports.
These delays can create significant financial difficulties, especially for businesses that rely on regular settlement payments to purchase inventory, pay suppliers, cover payroll, or finance daily operations.
Nevertheless, a successful payment transaction does not necessarily mean that the funds are immediately payable to the merchant.
Electronic payment transactions may pass through multiple stages involving authorization, capture, settlement, and merchant payout.
Depending on the agreement and applicable regulations, some transactions may also be subject to financial reserves, compliance reviews, or contractual settlement periods.
Therefore, an effective legal response begins by identifying where the funds are being held, which party is responsible for releasing them, and whether the settlement delay constitutes a contractual breach.
2. What Is the Difference Between a Successful Payment and a Completed Financial Settlement?#
One of the most important distinctions in electronic payment disputes is the difference between a transaction's technical status and the merchant's legal entitlement to receive its proceeds.
Depending on the payment method and processing system, a transaction may pass through several stages.
Payment Authorization
Authorization occurs when the relevant financial institution or payment system approves a transaction. However, authorization alone does not necessarily mean the funds have been captured or settled.
Payment Capture
Capture generally refers to the confirmation or completion of the payment collection process under the applicable payment mechanism.
Financial Settlement
Settlement involves the calculation and transfer of funds between the relevant financial participants according to the system's rules and timelines.
Merchant Payout
The merchant payout is the transfer of the merchant's net entitlement to the designated bank account after applicable fees, refunds, deductions, and other valid adjustments.
A transaction may therefore appear successful to the customer while its proceeds remain subject to settlement procedures or legitimate review requirements.
For this reason, merchants should examine both the contractual terms and the technical and financial records before concluding that the provider has failed to perform its obligations.
3. Can a Payment Service Provider Legally Withhold Merchant Funds?#
Not every delay or suspension of settlement constitutes an unlawful act.
Payment processing agreements may authorize providers to temporarily withhold funds under specified circumstances.
These may include:
Pending customer refunds.
Chargebacks or disputes initiated by cardholders.
Transactions requiring additional verification.
Contractually agreed financial reserves.
Incomplete merchant verification documentation.
Outstanding service fees or other contractual obligations.
Compliance reviews required under applicable laws or regulatory requirements.
However, the provider's ability to withhold funds is not unlimited.
The legality of a payment suspension depends on the contract, the circumstances of the transactions, applicable regulatory requirements, and whether the provider has complied with its contractual obligations.
Under Egyptian law, Article 147 of the Egyptian Civil Code, Law No. 131 of 1948, establishes the binding nature of contracts.
Article 148 further requires contractual obligations to be performed in accordance with the principles of good faith.
Accordingly, assessing whether withheld funds are legally justified requires examining the relevant contractual provisions, the reasons for suspension, and whether those reasons actually apply to the disputed transactions.
Simply describing a balance as “under review” or “temporarily suspended” does not, by itself, establish that withholding the funds is legally justified.
4. What Documents Are Required to Prove Outstanding Payment Settlements?#
A well-organized documentary record is essential when seeking to recover funds from a payment service provider.
The purpose of these records is to connect each completed transaction with its value, status, settlement deadline, and outstanding amount.
A. Payment Processing Agreement
Merchants should retain the agreement signed or electronically accepted with the payment service provider.
This includes contractual annexes, applicable terms and conditions, and relevant amendments.
Particular attention should be given to provisions governing settlement schedules, processing fees, financial reserves, payout suspensions, contractual objections, termination, and dispute resolution.
B. Payment Transaction Reports
Transaction reports should contain relevant information such as:
Transaction reference numbers (Transaction IDs).
Transaction dates.
Payment amounts.
Payment methods.
Transaction status.
Capture and settlement information.
Refunds and cancellations.
Chargebacks or disputed transactions.
These reports should be exported and preserved in reliable formats whenever possible.
Merchants should also comply with applicable data protection and payment security requirements and avoid retaining sensitive customer payment information without authorization.
C. Financial Settlement Statements
Settlement statements help establish which transactions have entered the settlement cycle and how the provider calculated the net amounts payable.
They should identify gross transaction values, fees, deductions, reserves, and net settlement amounts.
These records are particularly important when the merchant disputes the provider's calculations.
D. Bank Statements
Bank statements provide evidence of funds actually received.
They allow merchants to compare expected payouts with completed bank transfers and identify delayed or missing settlement amounts.
E. Invoices and Fulfillment Records
Invoices, delivery confirmations, service completion records, and other fulfillment documents may help establish that the underlying commercial transactions were genuine and completed.
F. Electronic Correspondence
Merchants should preserve emails, support tickets, suspension notices, settlement explanations, and any communications relating to payment delays.
These records may help establish the provider's stated reasons for withholding funds and document attempts to resolve the dispute.
G. Documents Supporting Disputed Deductions
Where the claim involves processing fees, penalties, refunds, or chargebacks, merchants should collect records showing the amount and basis of each deduction.
Not every dispute requires all these documents, but complete and accurate records can significantly strengthen a contractual payment claim.
5. How Can Merchants Calculate the Amount Legally Due?#
A successful payment total displayed in a merchant dashboard may differ from the amount actually due for settlement.
To determine the outstanding balance, businesses should reconcile eligible transactions against valid deductions and previous payouts.
A simplified calculation is:
Outstanding Settlement Amount = Transactions Due for Settlement − Valid Fees and Deductions − Previous Payouts
Any contractual reserves or transactions not yet eligible for payout should also be considered.
For example, assume a merchant has the following settlement records:
Financial Item | Amount |
|---|---|
Transactions due for settlement | EGP 350,000 |
Valid processing fees | EGP 10,000 |
Legitimate refunds and deductions | EGP 15,000 |
Previous payouts | EGP 250,000 |
Outstanding settlement balance | EGP 75,000 |
In this example, the remaining balance is EGP 75,000.
Provided that no additional contractual or legal adjustments affect its entitlement, this amount may form the basis of a documented financial claim.
Merchants should also prepare a separate schedule of disputed transactions showing the transaction number, date, value, settlement status, and grounds for objection.
Transactions legitimately pending settlement should not automatically be included in amounts claimed as immediately payable.
6. What Is the Legal Value of Electronic Payment Records?#
Disputes involving payment service providers frequently depend on electronic records rather than traditional paper documents.
These records may include payment gateway reports, transaction logs, settlement statements, electronic notifications, and email correspondence.
Egyptian Electronic Signature Law No. 15 of 2004 regulates certain aspects of electronic signatures, electronic writing, and electronic documents.
Article 15 addresses the evidentiary recognition of electronic writing and documents in civil, commercial, and administrative transactions, subject to the applicable legal and technical requirements.
Consequently, electronic transaction records may be relevant evidence in commercial disputes.
However, their admissibility and evidentiary weight depend on their nature, integrity, reliability, and compliance with applicable legal requirements.
Merchants should preserve original records where possible, avoid altering exported transaction files, and document when relevant reports were obtained.
In complex disputes, independent financial or technical experts may be needed to reconcile transaction histories, settlement reports, and banking records.
7. What Is the Contractual Process for Recovering Withheld Payments?#
When a payment service provider refuses or delays settlement, merchants should consider a structured approach based on the agreement and the circumstances of the dispute.
Step 1: Review the Contract and Settlement Terms
Identify the provider's settlement obligations, payout deadlines, contractual reserves, deduction policies, and dispute resolution procedures.
The first objective is to establish when the funds became legally due and which entity is responsible for payment.
Step 2: Prepare a Documented Financial Claim
Create a detailed reconciliation of outstanding transactions supported by payment reports, settlement statements, bank records, and fulfillment documents.
The claim should distinguish amounts currently due from pending or disputed transactions.
Step 3: Submit a Formal Objection
Send a written complaint or contractual objection identifying the outstanding amounts and requesting settlement.
The objection should also ask the provider to explain the legal or contractual basis for any withheld amounts or disputed deductions.
Step 4: Issue a Formal Legal Demand
If the issue remains unresolved, the merchant may consider sending a formal legal notice.
The notice should identify the relevant contractual obligations, the amounts claimed, the alleged breach, and the requested corrective action.
Any contractual notice requirements or applicable legal procedures should be followed.
Step 5: Negotiate an Amicable Settlement
Negotiation may be appropriate where the dispute concerns only part of the outstanding balance.
Potential solutions include releasing undisputed funds, correcting inaccurate deductions, or agreeing on a structured payment schedule.
Any settlement should be properly documented, including the amounts payable, payment deadlines, and whether it resolves all claims or only specific issues.
Step 6: Evaluate Arbitration or Litigation
If the dispute cannot be resolved through negotiation, the merchant should examine the applicable dispute resolution clause, governing law, jurisdiction, and potential costs.
The appropriate legal procedure will depend on the contractual relationship and the circumstances of the claim.
There is no universal settlement period applicable to every type of electronic payment transaction. Payment schedules may vary according to the agreement, the payment method, and applicable regulatory requirements.
8. What Is the Role of the Central Bank of Egypt in Regulating Payment Service Providers?#
Electronic payment systems and services in Egypt operate within a regulatory framework that includes the Central Bank and Banking System Law No. 194 of 2020.
Under this framework, the Central Bank of Egypt exercises regulatory and supervisory responsibilities over payment systems and payment services within the scope established by law.
These responsibilities extend to relevant categories of payment system operators and payment service providers.
On June 19, 2025, the Central Bank of Egypt announced licensing and registration rules for payment system operators and payment service providers.
The regulatory framework aims to strengthen the efficiency, security, and oversight of electronic payment services.
However, merchants should distinguish between a payment provider's regulatory obligations and its contractual responsibilities toward individual businesses.
Not every delayed settlement constitutes a regulatory violation.
Similarly, the existence of regulatory supervision does not necessarily mean the regulator will resolve every private commercial payment dispute.
Businesses should identify the provider's legal and regulatory status and determine which complaint procedures are applicable.
In some circumstances, regulatory complaint mechanisms may be relevant, but they do not necessarily replace contractual claims, arbitration, or litigation.
9. When Is Commercial Arbitration Appropriate for Payment Settlement Disputes?#
Payment processing agreements may contain arbitration provisions requiring disputes to be resolved outside ordinary court proceedings.
Egyptian Arbitration Law No. 27 of 1994 governs arbitration in civil and commercial matters within its scope of application.
The availability of arbitration depends on the existence of a valid arbitration agreement covering the relevant dispute.
Commercial arbitration may be particularly relevant in agreements involving international payment providers or cross-border business relationships.
However, before initiating arbitration, merchants should examine the agreed arbitration institution, seat of arbitration, procedural rules, language, costs, and potential enforceability of an award.
A commercial dispute does not automatically entitle one party to compel arbitration without a valid legal basis.
The appropriate dispute resolution mechanism must be determined by reference to the agreement and applicable law.
10. Can Merchants Claim Compensation for Delayed Settlements?#
Delayed payment settlements may cause financial harm beyond the amount originally withheld.
For example, a business may incur additional borrowing costs, face operational disruptions, or experience difficulties fulfilling commercial obligations.
However, a claim for compensation is legally distinct from a claim for payment of an outstanding balance.
While the principal financial entitlement may be established through transaction and settlement records, a damages claim generally requires proof of the applicable legal basis for liability, the damage suffered, and the legally required causal connection between the breach and that damage.
Under Egyptian law, Article 157 of the Civil Code addresses certain remedies for non-performance in reciprocal contracts, including performance or termination, with damages where legally justified.
Nevertheless, compensation is not automatically payable whenever a settlement is delayed.
Merchants should document any additional financial costs and assess whether those losses can legally be attributed to the provider's conduct.
11. Common Mistakes That Can Weaken a Merchant's Claim#
Several avoidable mistakes may undermine a merchant's position during a payment settlement dispute.
These include:
Relying on successful payment notifications without verifying capture and settlement status.
Failing to preserve transaction reports before account access becomes restricted.
Confusing gross payment volumes with net amounts legally due.
Missing contractual deadlines for submitting settlement objections.
Failing to identify the entity contractually responsible for making payouts.
Ignoring refunds, chargebacks, processing fees, or reserve provisions.
Signing final settlement agreements without reviewing their legal consequences.
Claiming financial damages without supporting documentation.
Maintaining accurate records and following contractual procedures can help reduce these risks.
12. How Can Businesses Prevent Future Payment Settlement Disputes?#
Preventing payment disputes begins with reviewing the payment processing agreement before selecting a provider.
Businesses should pay particular attention to settlement periods, processing fees, reserve policies, payout suspension provisions, objection procedures, and dispute resolution clauses.
They should also establish internal accounting controls to reconcile successful transactions, settlement reports, and actual bank transfers regularly.
Retaining dated copies of agreements, electronic terms, transaction records, and settlement statements can be particularly valuable when disagreements arise.
Businesses processing substantial payment volumes may also benefit from negotiating clearer contractual provisions concerning settlement deadlines, the release of withheld funds, and the handling of disputed deductions.
13. How Can Legal Counsel Help Recover Outstanding Payment Settlements?#
Payment settlement disputes often require a combination of legal, financial, and technical analysis.
The dispute may involve interpreting contractual obligations, reconciling transaction reports, reviewing processing fees, or determining whether a payout suspension was justified.
Legal counsel experienced in commercial disputes and digital contracts can assist businesses in reviewing payment service agreements, identifying contractual obligations, evaluating electronic evidence, and preparing formal legal demands.
Legal professionals may also assess whether negotiation, commercial arbitration, or litigation offers an appropriate approach in light of the amount claimed, the expected costs, and the circumstances of the dispute.
The objective is to develop a documented and legally supported recovery strategy while protecting the business's commercial interests.
Conclusion: Proving Successful Transactions Is Only Part of a Payment Recovery Claim#
When a payment service provider refuses to settle completed transactions, proof that customers successfully made payments is important but may not establish that the merchant is entitled to immediate settlement.
A properly supported claim requires reviewing the payment processing agreement, identifying amounts legally due, reconciling transaction records, preserving electronic evidence, and following the appropriate contractual dispute procedures.
Some settlement delays may be justified under contractual or regulatory requirements, while others may constitute breaches requiring further legal action.
If your business is experiencing delayed settlement of completed transactions, withheld merchant funds, or disputed payment processing deductions, consider requesting a professional legal review of your payment service agreement, transaction reports, and supporting documents to assess your rights and available recovery options.